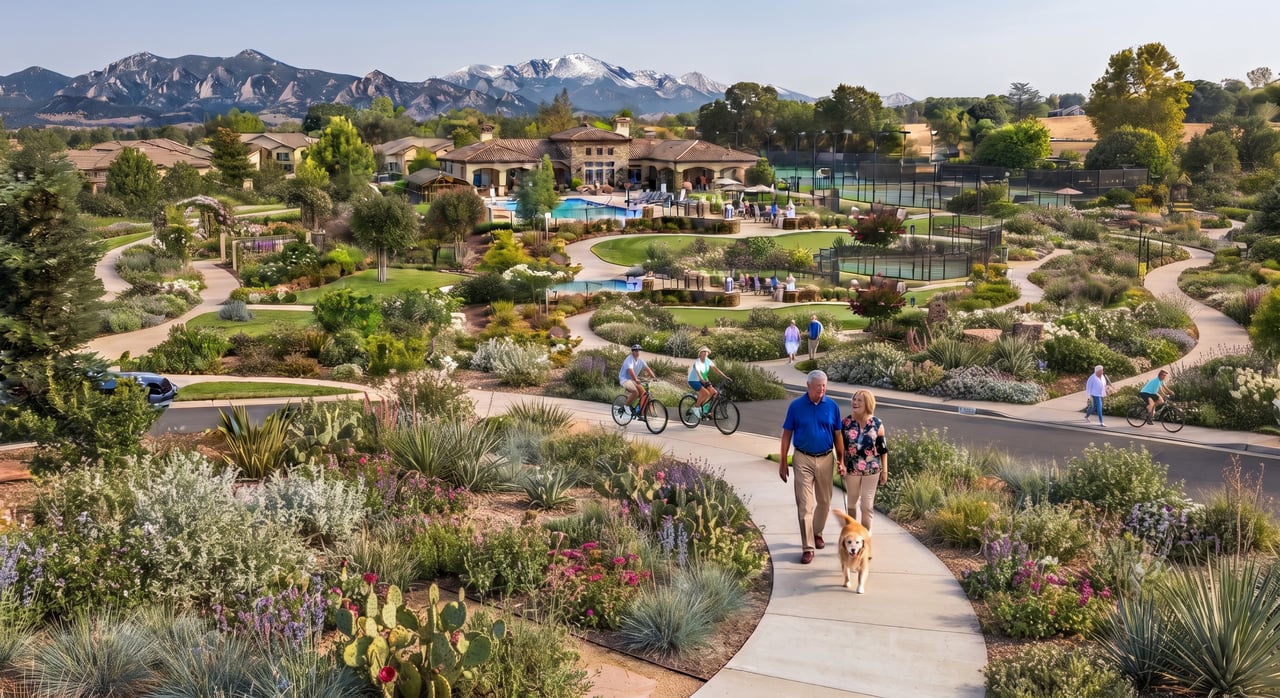
Retiring in Denver does not necessarily mean packing up and leaving Denver. And downsizing does not necessarily mean moving into a tiny condo, joining a 55+ community, or giving up the neighborhood and lifestyle you love.
For a lot of homeowners, retirement brings up a much bigger question:
Does the House I Have Now Still Make Sense for the Life I Want Next?
Maybe the kids are gone and you are maintaining rooms nobody uses. Maybe you are sick of stairs, yard work, snow removal, or spending your weekends taking care of a house. Maybe you have substantial equity and you are wondering whether some of that money could be doing something other than sitting in your home.
Or maybe your current house is completely paid off, you love it, and moving would actually cost you more every month.
That is why I do not think there is one “best place to retire in Denver.” There are too many variables, and retirement looks completely different from one person to the next.
Some people want a walkable Denver neighborhood where they can leave the car in the garage and walk to dinner. Some want a ranch-style home with fewer stairs and enough room for the grandkids. Some want a condo where somebody else worries about the roof and snow. Others specifically want a 55+ community with amenities, activities, and neighbors in a similar stage of life.
The better question is: What do you want your life, your housing, and your monthly expenses to look like for the next 10, 20, or 30 years?
Let’s start there.
If you are not yet sure whether you need to move, remodel, stay put, buy something smaller, or simply make a smarter use of your equity, start with my guide to right-sizing your Denver home. Retirement does not automatically mean downsizing. It may simply be the right time to make sure your current home still supports your next chapter.
In This Guide
- Whether Denver is actually a good place to retire
- How to define the retirement lifestyle you want before looking at homes
- Denver neighborhoods that may work for walkability, access, and long-term livability
- 55+ communities and active-adult living options around the Denver metro
- How to evaluate HOA fees, reserves, insurance, and maintenance obligations
- Whether downsizing will truly save you money
- How to think about buying before selling, selling before buying, or staying put
- What to consider if you want a home that works for both 60-year-old you and 80-year-old you
Is Denver Actually a Good Place to Retire?
For the right person, absolutely. But I would not tell anyone that Denver is automatically a great retirement destination just because I sell real estate here.
There are legitimate advantages. Denver has access to major healthcare systems, a large international airport, an enormous trail and park network, professional sports, museums, restaurants, live music, and easy access to the mountains. If your children or grandchildren already live in Colorado, staying nearby may be far more important than finding the state with the lowest property taxes.
You also have a huge variety of housing within the Denver metro. Retirement here could mean a condo in Cherry Creek, a smaller home in an established Denver neighborhood, a patio home in the suburbs, or a true 55+ active-adult community.
But Denver is not cheap.
Housing costs matter. Property taxes matter. Homeowners insurance has become an increasingly important part of the equation in Colorado. HOA dues can substantially change the monthly cost of a condo, townhome, patio home, or 55+ community. And if you are moving here from somewhere near sea level, yes, the altitude is real and worth considering too.
Then there is snow. If you are specifically trying to eliminate exterior maintenance from your life, buying another single-family home with a driveway, sidewalk, yard, and roof may not accomplish what you think downsizing is supposed to accomplish.
I would look at retirement in Denver the same way I look at any other real estate decision: Does the entire financial and lifestyle picture work for you?
Not just the purchase price.
If you are moving to Colorado from another state, or helping a parent or family member relocate closer to Denver, read my honest Colorado relocation guide. It covers the larger planning issues that matter beyond the listing photos: cost, lifestyle, geography, timing, and how to choose an area that fits how you actually live.
Before You Pick a Neighborhood, Figure Out What You Actually Want Retirement to Look Like
This is where I think people can get ahead of themselves.
It is really easy to start scrolling through listings and fall in love with a kitchen before you have figured out what problem you are actually trying to solve.
Before we talk about neighborhoods or communities, I would think about which of these sounds most like you.
I Want to Stay in the Middle of Everything
Maybe you are not remotely interested in “retirement living.”
You want restaurants. You want parks. You want coffee shops. You want concerts, museums, friends, and things happening around you. You may want to walk more and drive less.
In that case, an established Denver neighborhood or a condo in a walkable area may make much more sense than moving 30 miles outside the city just because somebody put that suburb on a “best places to retire” list.
Walkability is not just about whether a coffee shop is nearby. It can mean having practical services close to home: groceries, pharmacies, medical appointments, fitness options, restaurants, parks, trails, and places where you already spend time. That is a very different lifestyle from needing to drive 20 minutes every time you need something.
I Want Less House, but I Do Not Want a Retirement Community
This is a huge category.
You may simply want fewer bedrooms, less yard, less maintenance, or a home with a better layout. A smaller ranch, patio home, townhome, or condo could solve the problem without putting you in an age-restricted community.
And frankly, some people love the idea of a 55+ community. Other people hear “55+ community” and immediately know it is not for them.
Both are perfectly reasonable.
There is no rule that says retirement has to involve moving into a community designed around retirement. Plenty of homeowners want a smaller, more efficient home in a regular neighborhood where they can have friends, family, neighbors of all ages, and the lifestyle they already enjoy.
I Want Somebody Else to Handle the Maintenance
This is where condos, patio homes, townhomes, and some HOA communities can become very attractive.
But “maintenance-free” is a phrase I would examine very carefully.
What exactly is being maintained? Who pays for the roof? What happens when the association needs a major repair? How healthy are the reserves? What does the master insurance policy cover? Are there upcoming assessments?
A $300 HOA is not automatically better than a $600 HOA. I want to know what you are getting for the money and whether the association is financially healthy.
For a deeper breakdown of this issue, read the truth about Denver condos, rising HOA costs, and resale value. Before buying a condo, townhome, or patio home, I want buyers to review the reserve study, budget, board minutes, insurance certificate, maintenance responsibilities, and potential special assessments—not just the monthly HOA number.
I Want the Community and Amenities
This is where a true 55+ community may make a lot of sense.
Some people genuinely want the clubhouse, fitness facilities, social activities, golf, pools, walking trails, classes, clubs, and built-in community.
If you are moving after retirement and do not already have a large social network nearby, that can be a real benefit. A community with regular activities can make it easier to meet people, stay active, and create routines after a major life transition.
But amenities only matter if you will actually use them. A buyer who golfs three times a week may value a golf-oriented community very differently than a buyer who would rather have a nearby park, restaurant district, and a low-maintenance lock-and-leave condo.
I Want More for My Money
Then we probably need to look outside Denver proper.
The Denver metro has 55+ and active-adult communities in Aurora, Broomfield, Thornton, Castle Rock, Lakewood, and other surrounding areas. Depending on what you want, broadening the search can dramatically change the housing, lot size, floor plan, amenities, and price point available to you.
And this is why I would not start this search with a ZIP code.
I would start it with your life.
That same idea applies whether you are retiring, relocating, downsizing, or buying your first Denver home: the “best” area on paper may not be the area where you will actually be happiest. My guide to choosing the right Denver neighborhood for your real lifestyle can help you define what matters before you narrow the search.
Retirement Housing Options at a Glance
If This Sounds Like You | Housing Types Worth Exploring | What to Watch Closely |
|---|---|---|
I want walkability, restaurants, parks, and things to do. | Condo, townhome, smaller single-family home. | Parking, elevator access, unit layout, HOA health, actual walkability, and whether the location works for your daily life. |
I want less maintenance but do not want age restrictions. | Condo, townhome, patio home, paired home, smaller ranch. | What the HOA covers, exterior responsibilities, insurance, reserves, and future special-assessment risk. |
I want social opportunities and built-in amenities. | 55+ condo community or active-adult community. | Age restrictions, HOA costs, amenities you will actually use, rules, resale market, and proximity to family. |
I want a newer, one-level home. | Ranch, patio home, paired home, or active-adult new construction. | Metro district debt, HOA costs, taxes, lot size, distance from services, and whether “one level” still includes unavoidable stairs. |
I want to stay close to children and grandchildren. | Any housing type that fits your goals within a practical drive radius. | Traffic, drive time at the hours you will actually travel, proximity to everyday services, and whether the location still works if driving becomes harder later. |
Denver Neighborhoods Worth Considering for Retirement
There is not a magical list of neighborhoods where people suddenly become retirees at 65.
What I care about is whether the neighborhood and the housing stock support the way you want to live.
These are not the only Denver neighborhoods worth considering. The right answer depends on where your family lives, how often you want to drive, whether you want walkability, how much maintenance you want to keep, and what your monthly payment needs to look like. You can explore my Denver neighborhood guides to compare locations, housing styles, amenities, and lifestyle factors.
Cherry Creek
If your version of retirement involves walking to restaurants, shopping, coffee, and services, Cherry Creek deserves consideration.
There are condos and other lower-maintenance housing options that can provide more of a lock-and-leave lifestyle, particularly for someone who plans to travel frequently.
The tradeoff is obvious: Cherry Creek is not the budget option.
You also need to pay very close attention to HOA dues, what those dues include, the financial health of the association, parking, storage, pet rules, elevator access, and the actual layout of the unit.
A beautiful condo is not particularly useful if getting from the garage to your front door becomes a pain later. A building may be luxurious, but a unit can still be a poor fit if there are internal stairs, a difficult parking arrangement, limited storage, or a long and inconvenient path from the elevator to the front door.
Explore my Cherry Creek neighborhood guide if you are considering a central, amenity-rich Denver location where walkability and low-maintenance living may be more important than getting the most square footage for your money.
Washington Park and Platt Park
These areas can appeal to someone who wants to stay in an established Denver neighborhood with access to parks, restaurants, trails, and neighborhood amenities.
Washington Park offers the appeal of one of Denver’s most recognizable parks, tree-lined streets, and a strong neighborhood lifestyle. Platt Park can appeal to buyers who value historic character, South Pearl Street, restaurants, coffee shops, and a walkable neighborhood feel.
But the individual house matters tremendously.
A gorgeous older home with multiple levels, narrow stairs, laundry in the basement, and a bathroom configuration that does not work with future mobility needs may not be the smartest long-term purchase simply because you love the neighborhood.
This is where we have to evaluate the house and the location separately.
You may love the neighborhood and still decide that a particular property asks too much from you in terms of maintenance, stairs, lot size, snow removal, or ongoing renovation. There may be a better-fitting condo, townhome, smaller home, or main-floor-living option nearby.
Lowry
Lowry can be interesting because of its mix of housing, access to parks and trails, nearby amenities, and relatively central location.
Depending on what is available, you may find housing that offers a very different maintenance and accessibility profile from Denver’s older housing stock.
Lowry has a master-planned feel and a range of homes that can make it worth considering for buyers who want a more central Denver location without relying exclusively on historic housing. Review my Lowry neighborhood guide for more context on the area’s housing, amenities, and lifestyle.
Central Park
Central Park gives buyers access to newer housing, parks, trails, retail, and a variety of housing types.
Again, I would not say “Central Park is great for retirees” and leave it at that. Some homes may be fantastic for long-term accessibility. Others may have three stories and enough stairs to qualify as your daily cardio.
We need to look at the actual property.
Central Park may be worth exploring if you want newer construction, a more planned neighborhood environment, trail access, community amenities, and a mix of detached homes, townhomes, and condos. But newer construction does not automatically mean low maintenance, low cost, or better accessibility. You still need to evaluate the floor plan, HOA structure, taxes, any metro district obligations, and whether the location works for your actual routine.
Berkeley and West Highland
I am including these for the person who has zero interest in feeling retired.
You have restaurants, breweries, coffee shops, parks, neighborhood businesses, and relatively easy access to other parts of Denver.
Berkeley is particularly worth exploring for buyers who value parks, nearby lakes, Tennyson Street, local businesses, and an active northwest Denver lifestyle.
The challenge is finding the right housing configuration. These neighborhoods contain plenty of older homes, remodeled homes, newer construction, townhomes, and condos, and they are not remotely interchangeable when we are thinking about long-term accessibility or maintenance.
A fully remodeled house with a main-floor suite may be a very different long-term purchase from a charming bungalow with steep basement stairs, a detached garage, and a lot that requires more exterior upkeep than you want.
Other Denver Areas Worth Evaluating
Depending on your budget and lifestyle, it can also make sense to look at neighborhoods such as Park Hill, Cheesman Park, Ballpark, Lincoln Park, and Harvey Park.
Those areas do not offer the same housing stock, maintenance profile, walkability, pricing, or daily lifestyle. That is the point. “Retirement in Denver” is not one housing product. It can mean a lock-and-leave condo close to downtown, a smaller home near a major park, a low-maintenance townhome, or a more traditional single-family home in an established neighborhood.
What About Denver’s 55+ Communities?
This is where the Denver metro gets much more interesting than people sometimes realize.
There are true age-restricted communities throughout the metro, ranging from established condo communities to newer active-adult developments with clubhouses, fitness facilities, pools, golf, trails, and extensive social programming.
A few communities worth knowing about include:
Windsor Gardens in Denver
Windsor Gardens is one of the most established 55+ options in Denver itself.
For someone who wants the community component of active-adult living without leaving Denver proper, it is an obvious community to investigate.
The important word there is investigate.
I would want to look at the individual property, HOA structure, what the association covers, current financial documents, assessments, insurance, amenities, parking, accessibility, and any restrictions that could matter to you.
An established community can offer a lot of value, but it can also have older buildings, different maintenance needs, and HOA details that deserve close attention. Do not assume that every building, unit, floor plan, or monthly fee structure works the same way.
Heather Gardens in Aurora
Heather Gardens is another large, established 55+ community and offers a different housing and lifestyle option from buying a traditional single-family home.
This may appeal to someone prioritizing lower-maintenance living and community amenities, but again, the HOA and the specific property matter just as much as the name of the community.
Pay close attention to the unit’s location within the building, parking, elevator access, included utilities and services, association documents, reserve funding, building maintenance plans, insurance, and whether the community’s lifestyle is actually what you want.
Heritage at Eagle Bend in Aurora
For someone interested in a more golf-oriented active-adult lifestyle, Heritage at Eagle Bend belongs on the list of communities to explore.
It represents a very different retirement decision from buying a condo in central Denver, which is exactly why I like showing buyers the range of choices before they decide what they think they want.
If golf, community amenities, an active-adult setting, and a more suburban environment matter to you, it may be a strong fit. If being ten minutes from your grandchildren, favorite Denver restaurants, or existing friends matters more, it may not be.
Anthem Ranch in Broomfield
Anthem Ranch pushes the search north and offers the type of active-adult environment some buyers picture when they think about 55+ living.
For someone who values amenities, trails, recreation, and a community designed specifically around active adults, it can be worth considering.
But location matters. If your children and grandchildren live in Parker, choosing Broomfield because you love the clubhouse may get old pretty quickly.
Do the drive. Do it at the times you expect to make it. Visit the grocery store, a nearby medical office, restaurants, and the places you would regularly use. A fantastic house in a location that creates constant friction may not feel fantastic for long.
Heritage Todd Creek in Thornton
Heritage Todd Creek gives us another north-metro option and another opportunity to compare an active-adult community with traditional suburban housing.
The community is designed for active adults age 55 and better, but the right question is still not simply whether it is a 55+ community. The question is whether the house, monthly cost, amenities, HOA obligations, location, floor plan, and lifestyle are right for you.
Regency at Montaine in Castle Rock
For buyers who prefer newer construction and want to look south of Denver, newer 55+ options such as Regency at Montaine can offer a completely different product from Denver’s older established communities.
Newer does not automatically mean better. It means different.
You still need to understand HOA costs, future HOA responsibilities, taxes, insurance, location, accessibility, and what happens when you eventually resell.
New construction can also involve different considerations than an older resale home, including builder warranties, lot selection, landscaping responsibility, construction activity, metro district obligations, and whether the “finished community” you are imagining is actually complete.
Is a 55+ Community Actually Better Than a Regular Neighborhood?
Not necessarily.
It depends entirely on what you value.
A 55+ community can offer built-in social opportunities, amenities, and reduced maintenance. For someone who wants those things, that is fantastic.
But there are tradeoffs.
Age restrictions reduce the future buyer pool. HOA dues become part of your monthly housing expense. Rules may govern pets, parking, rentals, exterior changes, or other things you care about. And an HOA with gorgeous amenities still needs to have the financial health to maintain them.
A traditional neighborhood gives you a broader selection of homes and generally a broader resale audience, but you may be responsible for substantially more maintenance yourself.
Neither is inherently better.
The question is what you are buying with your money and whether you actually value it.
For example, a $650 monthly HOA could be a very good value if it covers exterior maintenance, roof responsibilities, landscaping, snow removal, water, sewer, trash, amenities, and meaningful insurance coverage. Or it could be a painful expense if it pays for amenities you never use while leaving you exposed to major assessments and rising insurance costs.
Do Not Look at the HOA Fee Without Looking at the HOA
This deserves its own section because I see people make this mistake all the time.
Imagine one community has a $350 monthly HOA and another has a $650 HOA.
The $350 one sounds better, right?
Maybe.
What if the $650 association covers exterior maintenance, roof, snow removal, landscaping, water, amenities, and a substantial master insurance policy, while the $350 association covers very little and has inadequate reserves?
Now we have an entirely different conversation.
Before buying into an HOA, particularly when you are choosing the property specifically because you want predictable maintenance in retirement, I want to understand:
- What does the HOA actually cover?
- How much money is in reserves?
- Are there current or anticipated special assessments?
- Who is responsible for the roof and exterior?
- What does the master insurance policy cover?
- Are there rental restrictions?
- What are the pet restrictions?
- Are major capital projects coming?
- How many owners are delinquent?
- How often have dues increased, and why?
- Are there pending insurance claims, litigation issues, or major deferred-maintenance concerns?
- Does the association have a recent reserve study, and is it funding the recommendations?
The monthly number by itself tells me almost nothing.
Denver condo and townhome buyers should also understand that HOA costs can reflect legitimate expenses that are getting more expensive: insurance, labor, building maintenance, utilities, reserve funding, and major capital projects. Read my full guide on Denver condo HOA costs, insurance, and resale value before you decide that a lower monthly HOA automatically means a better purchase.
Does Downsizing Actually Save You Money?
Not always.
This surprises people because “downsizing” sounds synonymous with “spending less.”
Suppose you have owned your current Denver home for 25 years and have either a tiny mortgage or no mortgage at all.
You sell it and buy a smaller, newer condo.
The condo costs less than the house you sold, but now you have a $600 monthly HOA. Your property taxes may be different. Your insurance is different. You have transaction costs. Depending on how you structure the purchase, you may have a mortgage again.
You absolutely may come out ahead.
But I want to do the math before we assume that you will.
This is also where your equity becomes part of a much larger conversation. Do you want all of it going into the next property? Do you want to free up some of it? Are you trying to eliminate a mortgage payment? Are you trying to reduce monthly expenses? Are you trying to preserve cash?
Those are different goals, and they can lead to very different housing decisions.
When comparing your current home with a possible replacement, I want to account for more than the purchase price. The comparison should include estimated sale proceeds, mortgage payment if applicable, property taxes, homeowners insurance, HOA dues, utilities, maintenance, exterior work, travel costs, and the value of time you are currently spending managing a house you may no longer want to maintain.
If you are considering this move, read my article on how to right-size your Denver home. It is designed to help homeowners distinguish between a move that genuinely improves their life and a move that simply creates a different set of expenses.
Should You Buy Your Next Home Before You Sell?
This is another one where there is not a universal answer.
If you have substantial equity in your current house, you may have plenty of money on paper but not necessarily have access to all of that money until the house sells.
Depending on your financial situation, there may be several ways to approach the transition.
- Some people sell first and then buy.
- Some buy first and sell afterward.
- Some make a purchase contingent on selling their existing property.
- Some use financing or other short-term strategies to bridge the gap.
- Some sell, put their belongings in storage, and rent temporarily because they would rather deal with moving twice than feel pressured into buying the wrong house.
I have zero interest in telling somebody they need to rush into their next home simply because their current one sold.
The goal is not merely to complete two transactions. The goal is to get the transition right.
For some people, selling first creates financial clarity and makes the next purchase easier. For others, it creates too much pressure to buy quickly. Buying first can provide more control over the move, but it can also mean carrying two homes temporarily, using a bridge strategy, or taking on additional financial risk. The right approach depends on your available equity, comfort level, cash reserves, timeline, and the type of property you are trying to buy.
Could a Reverse Mortgage Help You Buy Your Next Home?
Possibly, and this is one option many people do not realize exists.
For eligible homeowners who are at least 62, a Home Equity Conversion Mortgage, or HECM, can potentially be used to purchase a new primary residence. HUD refers to this as a HECM for Purchase.
That does not mean a reverse mortgage is automatically a good idea, and it certainly is not something I would recommend without involving a lender who specializes in them and, when appropriate, your financial and tax advisors.
The basic idea is that an eligible buyer can use HECM proceeds toward the purchase of a new primary residence while bringing sufficient funds to cover the remaining purchase price and closing costs.
There generally is not a required monthly principal and interest mortgage payment, but that does not mean living in the house is free. The homeowner is still responsible for property taxes, homeowners insurance, applicable HOA expenses, and maintaining the property.
HUD requires counseling for HECM borrowers, and the property must be used as a principal residence. A borrower’s ability to meet ongoing obligations such as property taxes and insurance is a meaningful part of the process. This is a specialized financial decision, not a casual real estate tool. HUD’s HECM information is a good starting point for understanding the program and locating approved counseling resources.
For the right person, it can be another tool worth evaluating. For somebody else, a conventional mortgage, cash purchase, sale-first strategy, or another financial approach may make much more sense.
I view it as an option to understand, not a product everyone over 62 needs.
Buy for 80-Year-Old You, Too
I think this is one of the most overlooked parts of buying a home around retirement.
You might be 60, healthy, active, and perfectly capable of running up and down stairs today.
Great.
But if you are buying a home you expect to keep for 20 years, I also want to think about whether 80-year-old you is going to hate 60-year-old you for buying it.
Look at things like:
- Can you live primarily on one level?
- Is there a bedroom and full bathroom on the main floor?
- Where is the laundry?
- How many stairs are required just to enter the house?
- Could the bathroom be modified later if necessary?
- Is there room for a walk-in shower if you ever need one?
- Who removes the snow?
- Who maintains the yard?
- Could you realistically stay there if your mobility changed?
- How far are you from healthcare, groceries, and the things you use regularly?
- Would you still be comfortable living there if driving became more difficult?
- Is the garage, driveway, entryway, and front door practical during a Denver winter?
- Does the floor plan make it easy to host grandchildren, caregivers, friends, or family members if your needs change?
You do not have to buy a house that looks like it was designed for someone 30 years older than you.
But future flexibility has value.
A home does not need to be perfectly accessible today to be a good long-term choice. But it should at least offer reasonable options. That might mean a main-level bedroom, a first-floor full bath, an attached garage, fewer exterior stairs, a manageable lot, or a floor plan that can be adapted without turning the entire house into a construction project.
If You Are Moving to Be Near Family, Start With the Family
This sounds ridiculously obvious, but it matters in a metro area this large.
If your children and grandchildren live in Arvada, I do not particularly care that somebody on the internet ranked Parker as the number-one place to retire.
That could turn every family dinner, soccer game, school event, and grandkid emergency into a substantial drive.
Denver metro geography matters.
If being close to family is one of the reasons you are moving, let’s figure out what “close” actually means to you first. Ten minutes? Thirty? An hour?
Then we build the housing search around that.
This is another reason I do not like generic “best places to retire” rankings. A place can have impressive amenities, attractive housing, and a beautiful clubhouse, but still be wrong for you if it puts too much distance between you and the people you are trying to be near.
What I Look at When Someone Is Buying a Home for Retirement
When I am helping someone choose a home they may live in for the next several decades, I am looking beyond whether they like the kitchen.
I am thinking about:
Long-term accessibility. Monthly carrying costs. Property taxes. Insurance. HOA finances. Maintenance exposure. Location. Healthcare access. Resale. Age restrictions. Future mobility. And whether the house still makes sense if life changes.
I am also looking at whether you are accomplishing the thing that made you consider moving in the first place.
If you wanted less maintenance and we somehow ended up looking at a 3,500-square-foot house on half an acre, we probably need to have a conversation.
If you wanted to free up equity and your new housing expenses are going to be higher than what you pay now, let’s make sure there is a damn good reason.
And if you discover halfway through the process that your current house actually makes more sense than anything we have looked at?
That is useful information too.
Buying and selling decisions are not successful simply because a transaction closes. The best outcome is one that makes your day-to-day life easier, protects your financial flexibility, and gives you options if your needs change later.
Frequently Asked Questions About Retiring in Denver
Is Denver a good place to retire?
It can be. Denver offers access to healthcare, recreation, cultural amenities, Denver International Airport, established neighborhoods, and a wide variety of housing. But housing costs, insurance, taxes, maintenance, altitude, and winter weather should all be part of the decision.
Are there 55+ communities in Denver?
Yes. There are 55+ and active-adult communities both within Denver and throughout the metro area, including communities in Denver, Aurora, Broomfield, Thornton, Castle Rock, Lakewood, and other surrounding areas.
Do I have to live in a 55+ community after I retire?
Absolutely not. Plenty of retired homeowners choose traditional single-family homes, condos, townhomes, or patio homes without age restrictions.
Is a condo better than a 55+ community for retirement?
Neither is inherently better. A condo may provide lower-maintenance living without an age restriction, while a 55+ community may offer more extensive social programming and amenities. HOA finances, monthly costs, location, accessibility, and lifestyle matter more than the label.
Should I sell my current house before buying my retirement home?
It depends on your equity, financing, comfort carrying two properties, the current market, and how much flexibility you want during the move. There are several ways to structure the transition, including selling first, buying first, using a sale contingency, or renting temporarily while you search.
Can I use a reverse mortgage to buy another house?
Eligible borrowers age 62 and older may be able to use a HECM for Purchase to buy a new primary residence. It is a specialized financial product with eligibility requirements, costs, counseling requirements, and ongoing homeowner responsibilities, so it should be evaluated with an experienced lender and appropriate financial professionals.
What should I look for if I want to age in place?
Think beyond what you need today. Main-level living, fewer stairs, bathroom configuration, laundry location, exterior maintenance, snow removal, proximity to healthcare, and the ability to modify the home later can all become important.
Will downsizing lower my monthly costs?
Not automatically. A smaller home can still have higher monthly costs if it comes with a mortgage, high HOA dues, increased taxes, increased insurance, or expensive maintenance. Compare the complete monthly picture before assuming a move will save money.
What HOA documents should I review before buying a condo, townhome, or 55+ property?
At a minimum, review the current budget, reserve study if available, reserve balance, board meeting minutes, master insurance documents, rules and regulations, rental restrictions, pet rules, any pending or recent special assessments, and major planned capital projects.
Not Sure Where Your Next Chapter Fits?
You do not need to know whether you want a condo in Denver, a ranch in the suburbs, or a 55+ community before we talk.
That is what the search process is for.
We can look at different types of housing, compare monthly costs and maintenance, explore Denver neighborhoods and 55+ communities, and figure out what actually makes sense before you commit yourself to a particular version of retirement.
Maybe the answer is selling the big house and buying something dramatically simpler.
Maybe it is moving closer to the grandkids.
Maybe it is choosing an active-adult community where somebody else deals with the snow.
Or maybe we run the numbers and you realize your current house is still the best damn option.
The point is not to move just because you have reached retirement. It is to make sure your home still fits the life you want to live.
Let’s Build the Right Plan Before You Move
Whether you are considering a walkable Denver condo, a one-level home closer to family, a lower-maintenance townhome, a traditional neighborhood, or a 55+ community with amenities, the first step is not rushing into listings.
The first step is understanding the lifestyle, location, monthly costs, maintenance exposure, and flexibility that make the most sense for you.
I can help you compare your current home with realistic alternatives, estimate likely sale proceeds, evaluate neighborhoods and communities, review the practical questions that matter before an offer, and create a plan for selling, buying, or deciding that staying put is the better move.
Explore Denver neighborhoods and start planning your next chapter.